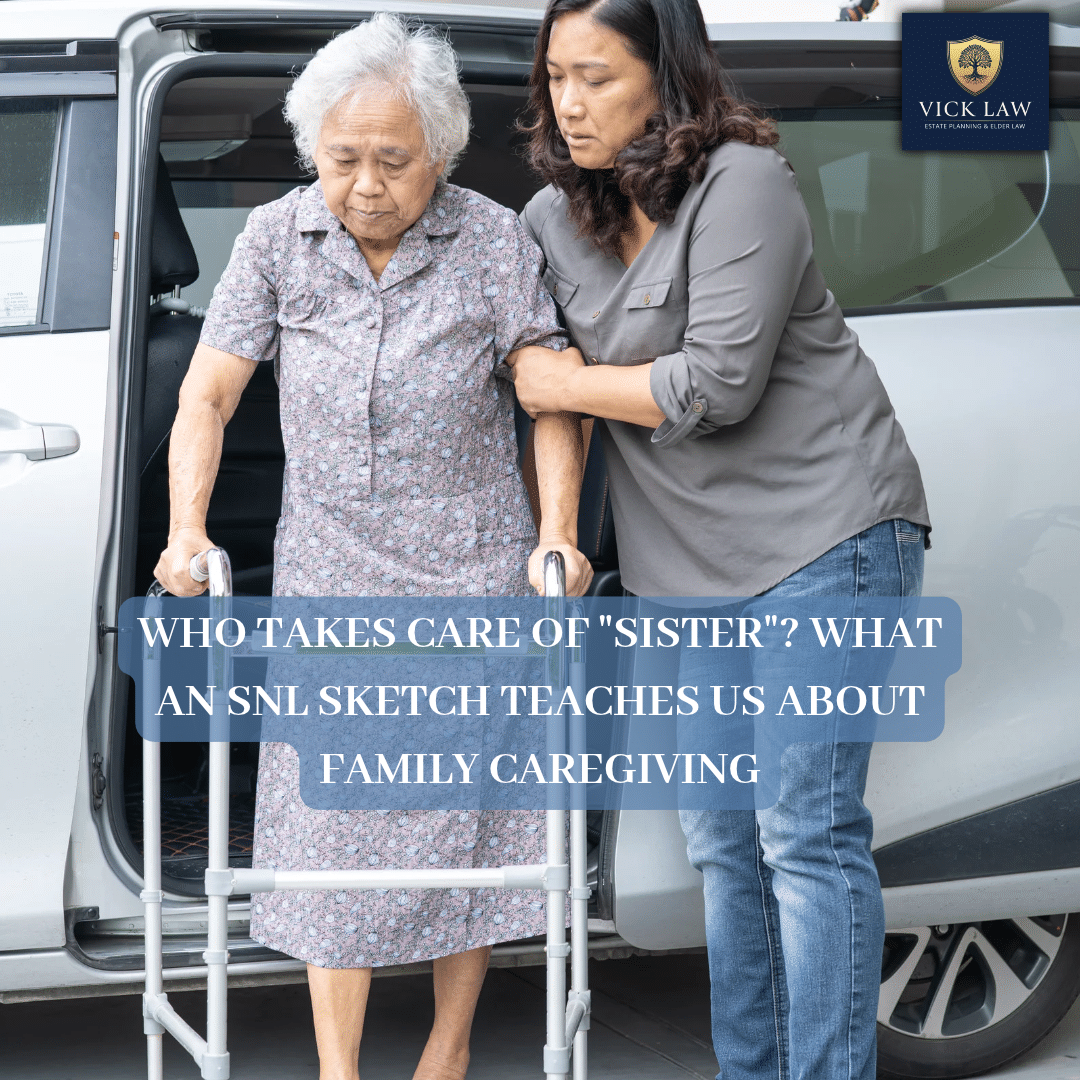
When one family member becomes the primary caregiver for aging parents, the responsibility can be overwhelming. Here's how families can share the load and why planning ahead matters.
Sometimes comedy hits a little too close to home. Saturday Night Live's sketch "Sister" is one of those moments. It's funny, exaggerated, and painfully familiar to anyone who has watched one family member become responsible for nearly everything involving aging parents.
There's always a "Sister."
She's the one taking Mom to appointments, managing Dad's medications, keeping up with the bills, and answering every phone call. She knows the doctors, the insurance information, and exactly which groceries her parents will eat. Meanwhile, everyone else assumes she's got it handled. We laugh because we recognize the situation. Maybe it's our own family. Maybe it's someone we know. Maybe we're the sister. Yet beneath the humor is a serious question:
Who's taking care of Sister?
It's a question more families need to ask, especially as adult children balance caregiving with their own families, careers, and responsibilities.
When One Person Becomes Responsible for Everything
Most families don't intentionally decide that one person should handle all their parents' care. It happens gradually. Mom needs a ride to the doctor. Dad needs help sorting out an insurance bill. Someone has to pick up prescriptions or arrange for repairs around the house. One child steps in because they're nearby, available, or simply the person who always takes care of things. Before long, that person has become the family's unofficial care coordinator and the first person everyone calls when something goes wrong. The other siblings may love their parents just as much. They may even believe they're contributing. Yet there's a difference between occasionally helping and being responsible for making sure everything gets done. Much of caregiving involves work no one sees. It's remembering appointments, anticipating problems, researching care options, and worrying about what might happen next. That responsibility doesn't disappear when the caregiver goes home.
The Sandwich Generation: Caring for Everyone Except Yourself
For many adults, caregiving comes at a particularly demanding stage of life. They're part of the sandwich generation, caring for aging parents while still supporting their own children. Some are helping with grandchildren, too. Imagine a woman in her 50s. She's coordinating her mother's medical appointments, checking on her father, helping a teenager prepare for college, and occasionally watching her grandchildren. She also has a full-time job, a household to manage, and her own retirement to consider.
Where does she find time for herself?
Caregiving can affect a person's health, marriage, career, and finances. Some caregivers reduce their work hours or miss opportunities because their parents need assistance. Others put off their own medical appointments or struggle to find time to rest. Over time, these demands can lead to caregiver burnout. Exhaustion, irritability, anxiety, sleep problems, and feelings of resentment can all be signs that someone needs additional support.
Loving your parents doesn't mean you have an unlimited capacity to care for them.
Recognizing that limitation isn't selfish. It's necessary.
How Can Families Better Support "Sister"?
One of the most meaningful ways to support a family caregiver is to stop assuming that because they're handling everything, they don't need help. Siblings may live in different cities, have demanding careers, or face financial limitations. Responsibilities won't always be divided equally, but everyone should consider what they can reasonably contribute.
A sibling who lives nearby might handle grocery shopping or transportation. Someone farther away could manage insurance paperwork or coordinate appointments. If finances allow, family members might contribute toward respite care or in-home assistance. Most importantly, don't make the primary caregiver responsible for coordinating everyone else's help. There's a difference between saying, "Let me know if you need anything," and saying, "I'll take care of Mom's prescription refills and insurance calls." One offers help. The other takes something off her plate. Families should also recognize that the caregiver needs time away from caregiving. A weekend off or reliable backup assistance can make a meaningful difference.
Supporting the caregiver is part of caring for your parents.
Create a Family Care Plan Before There's a Crisis
Too often, families wait until a parent falls, receives a difficult diagnosis, or can no longer live independently before discussing long-term care. Suddenly, everyone has questions. Who will help Mom at home? Who can make medical decisions? How will care be paid for? Does anyone know where the important documents are? These conversations are easier when parents can still participate in decisions about their future.
Start by asking what matters most to them. Would they prefer to remain at home as long as possible? What concerns do they have about needing assistance? Have they considered how they would pay for long-term care? Then discuss what family members can realistically provide. Maybe one child can manage appointments while another handles financial paperwork. Perhaps the family needs to arrange professional assistance rather than expecting one person to provide daily care. Parents should also make their wishes known and identify who they trust to make decisions if they become unable to do so. The family should know where important documents are kept and understand what resources may be available to help pay for care.
Put the plan in writing and revisit it as circumstances change. The goal isn't to predict every challenge. It's to prevent one person from becoming responsible for every decision simply because no one planned otherwise.
How Can Estate Planning Make Caregiving Easier?
When people think about estate planning, they often focus on what happens after someone dies. For aging parents, some of the most important planning concerns what happens while they're still living. Imagine a daughter helping her father manage his finances as his memory begins to decline. If he becomes unable to handle financial matters and hasn't signed an appropriate power of attorney, she may have limited authority to act on his behalf. Depending on the circumstances, the family might need to pursue guardianship through the court. Planning ahead can help establish appropriate decision-making authority and reduce uncertainty. A durable financial power of attorney allows a parent to authorize someone to handle specified financial matters, such as paying bills or managing accounts.
Healthcare representative appointments and advance directives can help identify who may make healthcare decisions when necessary and communicate certain medical treatment preferences.
For some families, a revocable living trust may provide a structure for managing assets if a parent becomes incapacitated. A properly designed and funded trust can allow a successor trustee to step in under the circumstances described in the document. These documents don't replace the need for family cooperation. They help clarify legal responsibilities and give the people providing care a better understanding of their authority. Just as importantly, the person named to handle financial decisions doesn't necessarily need to be the person managing every aspect of daily care.
Could a Medicaid Asset Protection Trust Help Your Family Prepare for Long-Term Care?
Although it is ideal for parents to be able to stay in their own home, it may to be feasible. One of the greatest concerns families face when planning for aging parents is how they will pay for care. Long-term care can be expensive, particularly when someone needs ongoing assistance or nursing home care. Families may worry about how those costs will affect a parent's savings, home, and financial security. This is where early planning becomes particularly important.
For some families, a Medicaid Asset Protection Trust (MAPT) may be worth considering as part of a broader long-term care plan. A MAPT is a type of irrevocable trust designed to hold certain assets under specific legal restrictions. When properly established and funded, it may help families plan for future Medicaid eligibility while addressing concerns about preserving assets for a spouse or future generations. For example, parents who own a home may want to explore whether placing it into a properly structured MAPT makes sense as part of their long-term care planning. Depending on the circumstances, this approach may help address how the property is treated for Medicaid purposes if nursing home care becomes necessary later.
However, a MAPT doesn't automatically make someone eligible for Medicaid or guarantee that particular assets will be protected. Indiana Medicaid has specific eligibility rules, transfer restrictions, and estate recovery provisions that must be considered. Timing matters, too. Transfers into certain irrevocable trusts can be subject to Medicaid's five-year look-back period for long-term care benefits. Establishing a trust shortly before care is needed may create eligibility problems rather than solve them.
A MAPT also involves giving up certain rights and control over assets placed into the trust. That trade-off deserves careful consideration. The purpose of planning isn't simply to move assets into a trust. It's to understand how a family's resources might support future care needs, whether Medicaid benefits may eventually be available, and what financial arrangements make sense for everyone involved. When parents address these questions early, their children may be better prepared to navigate long-term care decisions without having to make every financial choice during a crisis. For the family caregiver, that preparation can provide something valuable: a clearer understanding of the options available when a parent's care needs increase.
What Resources Are Available for Family Caregivers?
Families sometimes assume their only options are to provide all the care themselves or move a parent into a nursing home. Depending on the parent's needs and circumstances, other services may be available. In Indiana, families can contact their local Area Agency on Aging for information about community programs, caregiver support, and long-term care resources.
Indiana's INconnect Alliance can help families locate services for older adults and individuals with disabilities. Indiana 211 offers information about community assistance programs. Organizations such as AARP and the Alzheimer's Association also provide caregiver education and support resources. Families may want to explore respite care, adult day services, transportation assistance, or in-home care. Availability and eligibility vary, but learning about these services before they're urgently needed can help families prepare.
Parents, You Can Help Your Children by Planning Now
Most parents would never intentionally place the entire responsibility for their care on one child. Yet without a plan, that's sometimes what happens. If you're a parent, consider what your children would need to know if you suddenly required assistance. Do they know where your important documents are? Have you selected someone to make financial and healthcare decisions if needed? Have you discussed your preferences for long-term care? Perhaps most importantly, have you considered how your care might affect their own families? You can't anticipate every future need, but you can make your wishes known, organize important information, and involve your children in planning.
Planning for your future is also a way of caring for the people who may one day care for you.
How Vick Law Can Help Your Family Prepare
At Vick Law, we understand that aging and long-term care planning involve more than legal documents. They involve family relationships, financial concerns, and difficult decisions about the future. Our mission is to help families in Greenwood, Center Grove, Johnson County, and Southside Indianapolis understand their estate planning and elder law options. That may include preparing powers of attorney, healthcare directives, wills, and trusts. We also help families explore Medicaid planning strategies, including whether a Medicaid Asset Protection Trust may be appropriate for their circumstances.
We want your family to understand their options, prepare for potential long-term care expenses, and establish legal arrangements that reflect their wishes. Communication is everything. We encourage families to begin these conversations early, while parents can still participate and everyone has time to consider the decisions ahead. Legal planning can't guarantee that siblings will share caregiving responsibilities or that every decision will be easy. It can help families prepare and reduce some of the uncertainty that makes caregiving more difficult.
Who's Taking Care of Sister?
The SNL sketch is funny because so many families recognize the situation. There's the sibling who does everything. The siblings who assume everything is fine. The parents who need more help than anyone expected. The laughter fades a little when you consider how many families are living some version of that story.
If you're the primary caregiver, you deserve support and a voice.
If you're a sibling, consider what you can take off the caregiver's plate.
If you're a parent, don't wait until your children are overwhelmed to begin planning.
The best time to support "Sister" is before she becomes the family's entire care plan. If your family hasn't had these conversations, now is a good time to start. Vick Law can help you understand your legal options and develop an estate plan tailored to your family's needs. Book a free consultation today.
Vick Law, P.C.
3209 W. Smith Valley Rd., Suite 113
Greenwood, IN 46142
(317) 884-3133
www.VickLaw.org
This article is provided for educational purposes only and does not constitute legal advice or create an attorney-client relationship. Estate planning, Medicaid eligibility, and long-term care options depend on individual circumstances and applicable law.
Reference: Saturday Night Live. (2026, November 14). Sister [Video]. YouTube. https://www.youtube.com/watch?v=-X9dxL17t1k